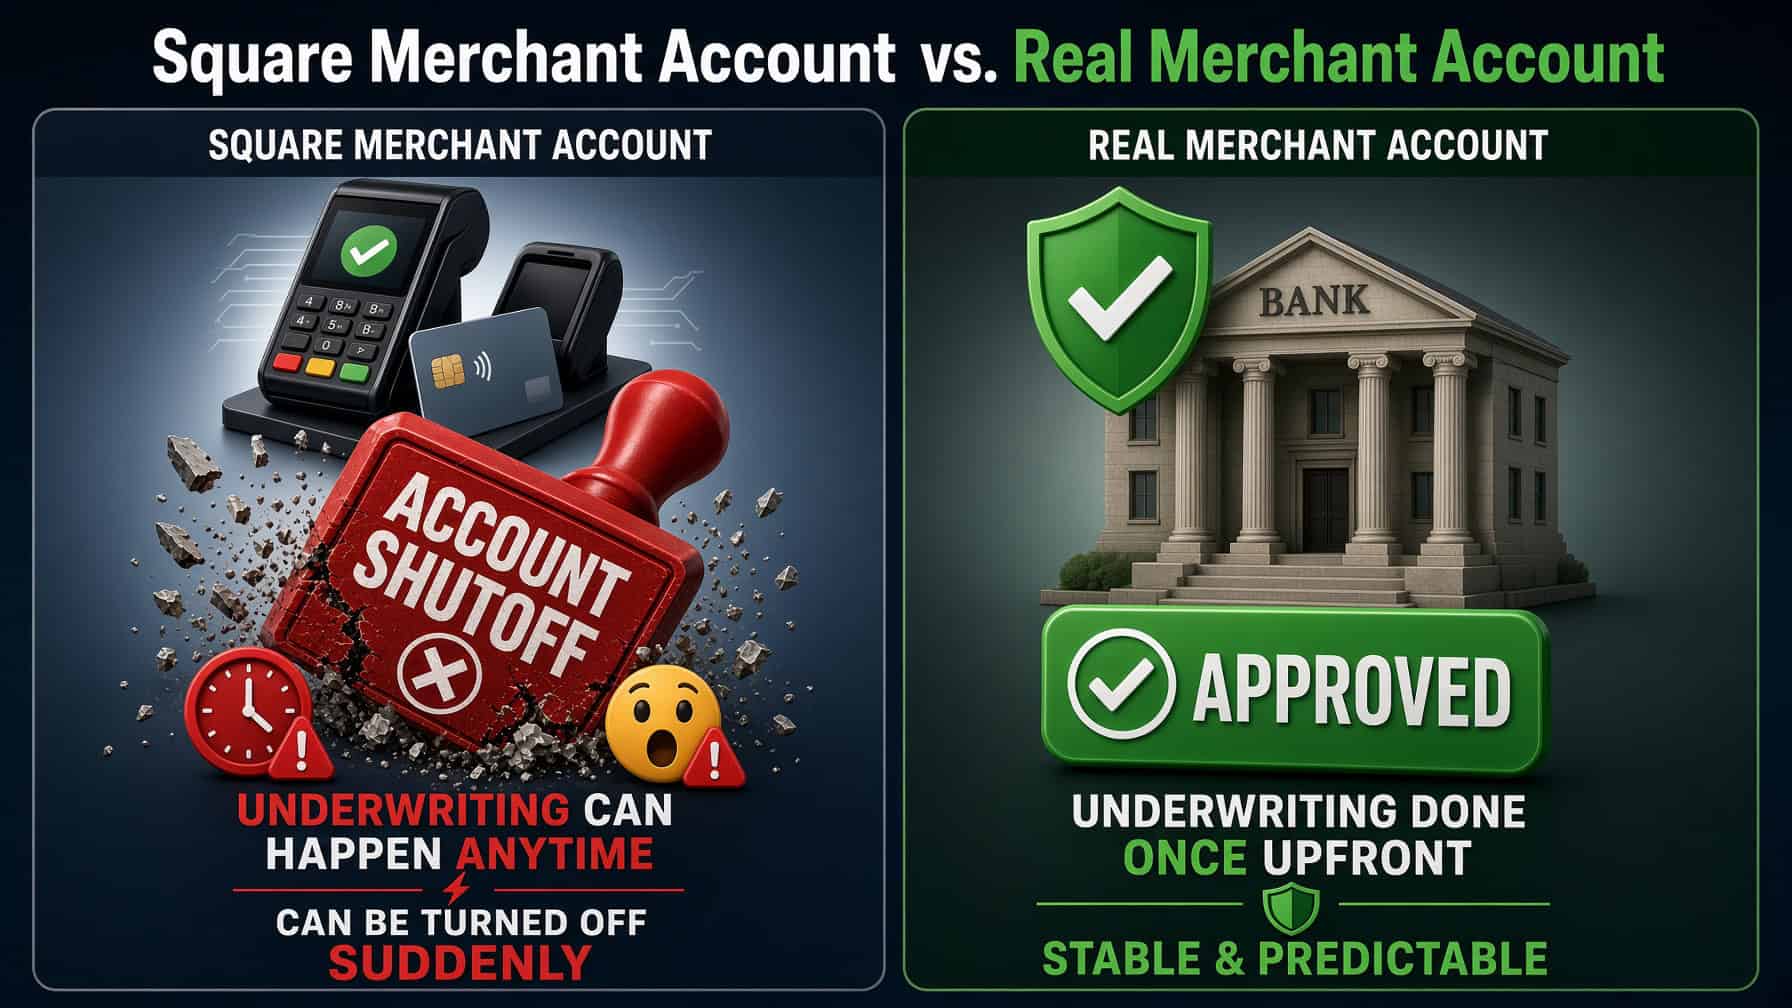
A Square merchant account isn’t the same thing as a real, dedicated merchant account, and that difference is exactly why Square, Stripe, and PayPal can genuinely freeze your business’s money, sometimes for months, with little warning. It’s not a rare edge case. These apps pool thousands of businesses under one shared account behind the scenes, and when their system flags any business in that shared pool as risky, it can freeze funds first and sort out the details later, including yours, even if you did nothing wrong.
A traditional business bank account for card processing (called a merchant account) works differently: your business gets its own approval, on its own, with none of that shared exposure. This page covers why the popular apps behave this way, when using one is still a reasonable choice, and what to actually watch for.
A temporary hold on your money is frustrating, sometimes financially painful, but eventually it can be resolved. Getting cut off for good is a different problem. If a payment app terminates your account for too many disputed charges or a rule violation, you can end up on Mastercard’s Terminated Merchant File, a shared list that other processors check before approving a new business. Landing on it can make it genuinely hard to get approved anywhere else for up to five years. Apps like Square and Stripe are known for cutting businesses off faster and over smaller issues than a traditional merchant account would, because they’re protecting a shared pool of businesses, not evaluating yours individually.
That’s the part most advice on this topic leaves out: it’s not just “will my money get held for a while?” It’s “could this follow my business for half a decade?”
This isn’t the app being careless it’s how they’re built. Square, Stripe, and similar apps are what’s formally called a payment aggregator (or “payment facilitator,” PayFac for short). One company holds a single master account with a bank, and every business using the app is bundled underneath it as a sub-account.
The app itself isn’t directly answerable to Visa or Mastercard; its own bank is, for the entire group of businesses under that one account, not just yours. When the bank’s exposure covers thousands of businesses at once, the fastest way to protect itself is to act quickly on anything that looks risky, even if that one business turns out to be completely fine.
A traditional merchant account skips that shared exposure entirely: your business gets its own approval and its own standing with the bank, so another business’s problem never becomes yours.
In December 2025, Stripe cut off Flipcause, a donation platform used by thousands of nonprofits, freezing roughly $2.2 million in the process. The trigger: Mastercard had warned Stripe that Flipcause wasn’t paying nonprofits their donations on time, and Stripe itself faced up to $6 million in potential fines tied to Flipcause’s account. Flipcause filed for bankruptcy days later, owing more than $29 million to over 3,000 nonprofits.
This isn’t a story about Stripe being careless; Stripe had a real, documented exposure to manage. That’s exactly the point: this business model means a platform protecting itself can move fast and hit hard, regardless of how things actually shake out for the business (or in this case, thousands of nonprofits) caught underneath it.
None of this means these apps are a bad choice across the board; there are real situations where they make sense: very low or unpredictable monthly sales, the first few months of a new business with no track record yet, or simply not wanting to commit to a monthly minimum while things are still getting off the ground. The setup speed and simplicity are real advantages at that stage.
The real question isn’t “these apps or a merchant account, forever.” It’s knowing when your business has actually outgrown the trade-off.
These apps typically charge a flat rate around 2.6-2.9%+ per sale. A dedicated merchant account can run meaningfully cheaper at real volume, though it usually comes with a monthly fee the apps don’t charge. Where the two actually cross depends on your card mix and industry, but a concrete example shows the gap: a business doing $500,000/month in sales pays roughly $14,500/month at a 2.9% flat rate, versus roughly $8,000–$10,000/month on a well-structured merchant account, a real, six-figure gap over a year at that volume. That gap can close even further with dual pricing, which eliminates the card processing cost on a merchant account entirely rather than just lowering the flat rate a Square merchant account charges.
Most estimates put the practical crossover somewhere between $10,000 and $30,000/month in sales, depending on the business. Below that, the app’s simplicity may genuinely outweigh the cost difference. Above it, the math starts to clearly favor a dedicated account on top of the risk difference covered above.
Not every freeze is the same, and knowing which kind you’re dealing with changes what to do next:
Knowing which one you’re actually dealing with before assuming you can just switch and move on is the real first step.
Want to know whether your business has already outgrown a Square merchant account? Get a free comparison →