
Managing a handful of locations with a basic setup and managing a genuine Enterprise POS deployment across dozens, hundreds, or more locations are two completely different operational problems. A basic multi-location POS setup can usually keep a small group of stores in sync.
At real enterprise scale, that same setup breaks down: someone ends up manually pushing menu or price updates to each location one at a time, or waiting on IT to physically touch every terminal for a software update. This page covers what an actual Enterprise POS platform needs to do differently, and why that gap matters more as a business grows past a handful of locations.
A lot of POS platforms market themselves as multi-location-ready, but most of that capability tops out well before real enterprise scale. The genuine dividing line isn’t the number of locations on its own; it’s whether changes and updates can actually be deployed everywhere at once, remotely, without someone touching each location individually. Paramount’s enterprise-tier POS platform is built specifically for multi-concept and multi-unit operations running into the thousands of branches, not as a stretch use case, but as the actual designed purpose of the tier.
The operational cost of a system that isn’t built for this scale grows faster than the number of locations does. At five locations, manually pushing an update to each one is annoying but survivable. At fifty or five hundred, it becomes a real bottleneck that slows down every price change, every menu update, every policy rollout, and it’s exactly the kind of hidden operational drag that doesn’t show up on a spreadsheet until it’s already a problem. A platform built for real enterprise deployment removes that bottleneck entirely, rather than just making it slightly less painful.
Like Paramount’s franchise-tier platform (see our guide to franchise software), the enterprise tier runs both restaurant and retail operations on the same underlying system, genuinely relevant for a large group that operates more than one type of concept, or is consolidating multiple acquired brands onto a single platform. The difference at enterprise scale is depth: multi-concept support isn’t just a feature checkbox; it’s built to handle real operational complexity across dozens of distinct brand configurations at once.
The same real, named back-office integrations available at the franchise tier carry through at enterprise scale, where they matter even more: Restaurant365 for full accounting and back-office management, Shogo for automated bookkeeping sync, ADP for payroll and workforce data across every location, Octopus Bridge for AI-powered inventory visibility network-wide, Dash Solutions for real-time tip payouts, and Factor4 for gift card management across the whole enterprise. On the delivery side, DoorDash Drive and Uber Direct both connect at the same enterprise level as they do for a single location.
Want to know what real Enterprise POS support would actually look like for your business? Get a free comparison →
Franchising is a genuinely massive part of the U.S. economy, with an estimated 845,000 franchise establishments in 2026, employing nearly 8.9 million people and generating over $921 billion in economic output. But running a franchise creates a specific franchise software problem that a single-location guide never has to solve: it’s not enough for one store to run well. Every location has to run the same way same menu, same pricing, same reporting while still letting local managers actually manage their store day to day.
This page covers what actually goes wrong without a real multi-location POS system, and what a franchise-ready platform needs to do that a single-store system doesn’t.
A POS system that works fine for a single store often falls apart the moment a second or third location gets added. Inventory counts stop matching between locations. Reports come back in different formats depending on who’s running them. And a transaction that gets logged to the wrong location doesn’t just create a bookkeeping annoyance at a franchise; it can throw off royalty calculations, since most franchise royalty structures are based on accurately reported sales per location. That’s a real, specific risk that doesn’t exist for a standalone business.
Most POS platforms specialize in one vertical or the other. That’s a real limitation for a franchise group that operates more than one type of concept, or is considering expanding into a second one. Paramount’s multi-location POS platform runs both restaurant and retail operations on the same underlying system. Full-service and quick-service restaurants, pizzerias, coffee shops, and retail formats including apparel, convenience, and specialty grocery are all explicitly supported, including franchise operations. That means a franchise group doesn’t need to learn, staff, and maintain two entirely separate systems just because it operates two different kinds of stores.
Consistency isn’t just about back-office reporting it’s also about what the customer actually experiences walking into any location in the network:
A single-location business can often get by without deep back-office integrations while a multi-location operation can’t. The platform genuinely connects to real, named tools built for exactly this scale: Restaurant365 for full accounting and back-office management, Shogo for automated bookkeeping sync, ADP for payroll and workforce data, Octopus Bridge for AI-powered inventory visibility across locations, Dash Solutions for real-time tip payouts, and Factor4 for gift card management.
On the delivery side, orders placed through a location’s own ordering system can be fulfilled through DoorDash Drive or Uber Direct. Uber’s commission-free delivery network for orders that don’t originate from the Uber Eats marketplace app itself.
Want to know what the right franchise software would actually look like for your business? Get a free comparison →

Roughly a quarter of small businesses still don’t have a website; commonly cited estimates put it somewhere between 17% and 29%, with the number steadily shrinking each year as more businesses come online. What most owners in that position don’t realize: not having a website doesn’t mean you’re locked out of ecommerce. A POS system alone can generate a real, working online store, with no separate website project required.
This page covers the real ecommerce platforms a payment system can actually plug into, and the specific, different path available if you don’t have a website at all yet.
This is the part most guides skip, because it assumes every business already has a website to build on. Some real POS platforms, Clover among them, include their own built-in online ordering page: a simple, hosted page with your live menu or product list that customers can order and pay from directly, generated straight from what’s already set up in your POS. No separate site to design, host, or maintain; when you update a price or item in-store, the online page updates with it automatically.
For a business that wants a fuller online store and a real product catalog, not just a simple ordering page, the payment side plugs directly into the ecommerce platforms most businesses already recognize: BigCommerce, Shopify, WooCommerce, and Adobe Commerce (Magento). These are real, named integration partners, not a generic claim. Clover specifically partners with BigCommerce to help a merchant launch a new store from scratch, complete with customizable templates and secure checkout, while Shopify and WooCommerce are common paths for a business that already has a site and just needs payment processing wired into it correctly.
The practical difference between these two paths is worth knowing upfront:
This is the real, practical risk of treating online and in-store sales as two separate systems: a customer buys the last one of something online while another customer is holding the same physical item at your register. Whoever completes their sale second gets an item that’s no longer actually there. A POS-integrated ecommerce setup keeps inventory synced automatically across both channels from one dashboard, instead of someone manually updating two separate counts and hoping they stay accurate. (This connects directly to a broader problem covered in our guide to what actually matters in a retail POS: inventory accuracy affects a lot more than just your online store.)
Beyond the storefront itself, a real integration typically includes:
Want to know what adding ecommerce would actually look like for your business, website or not? Get a free comparison →
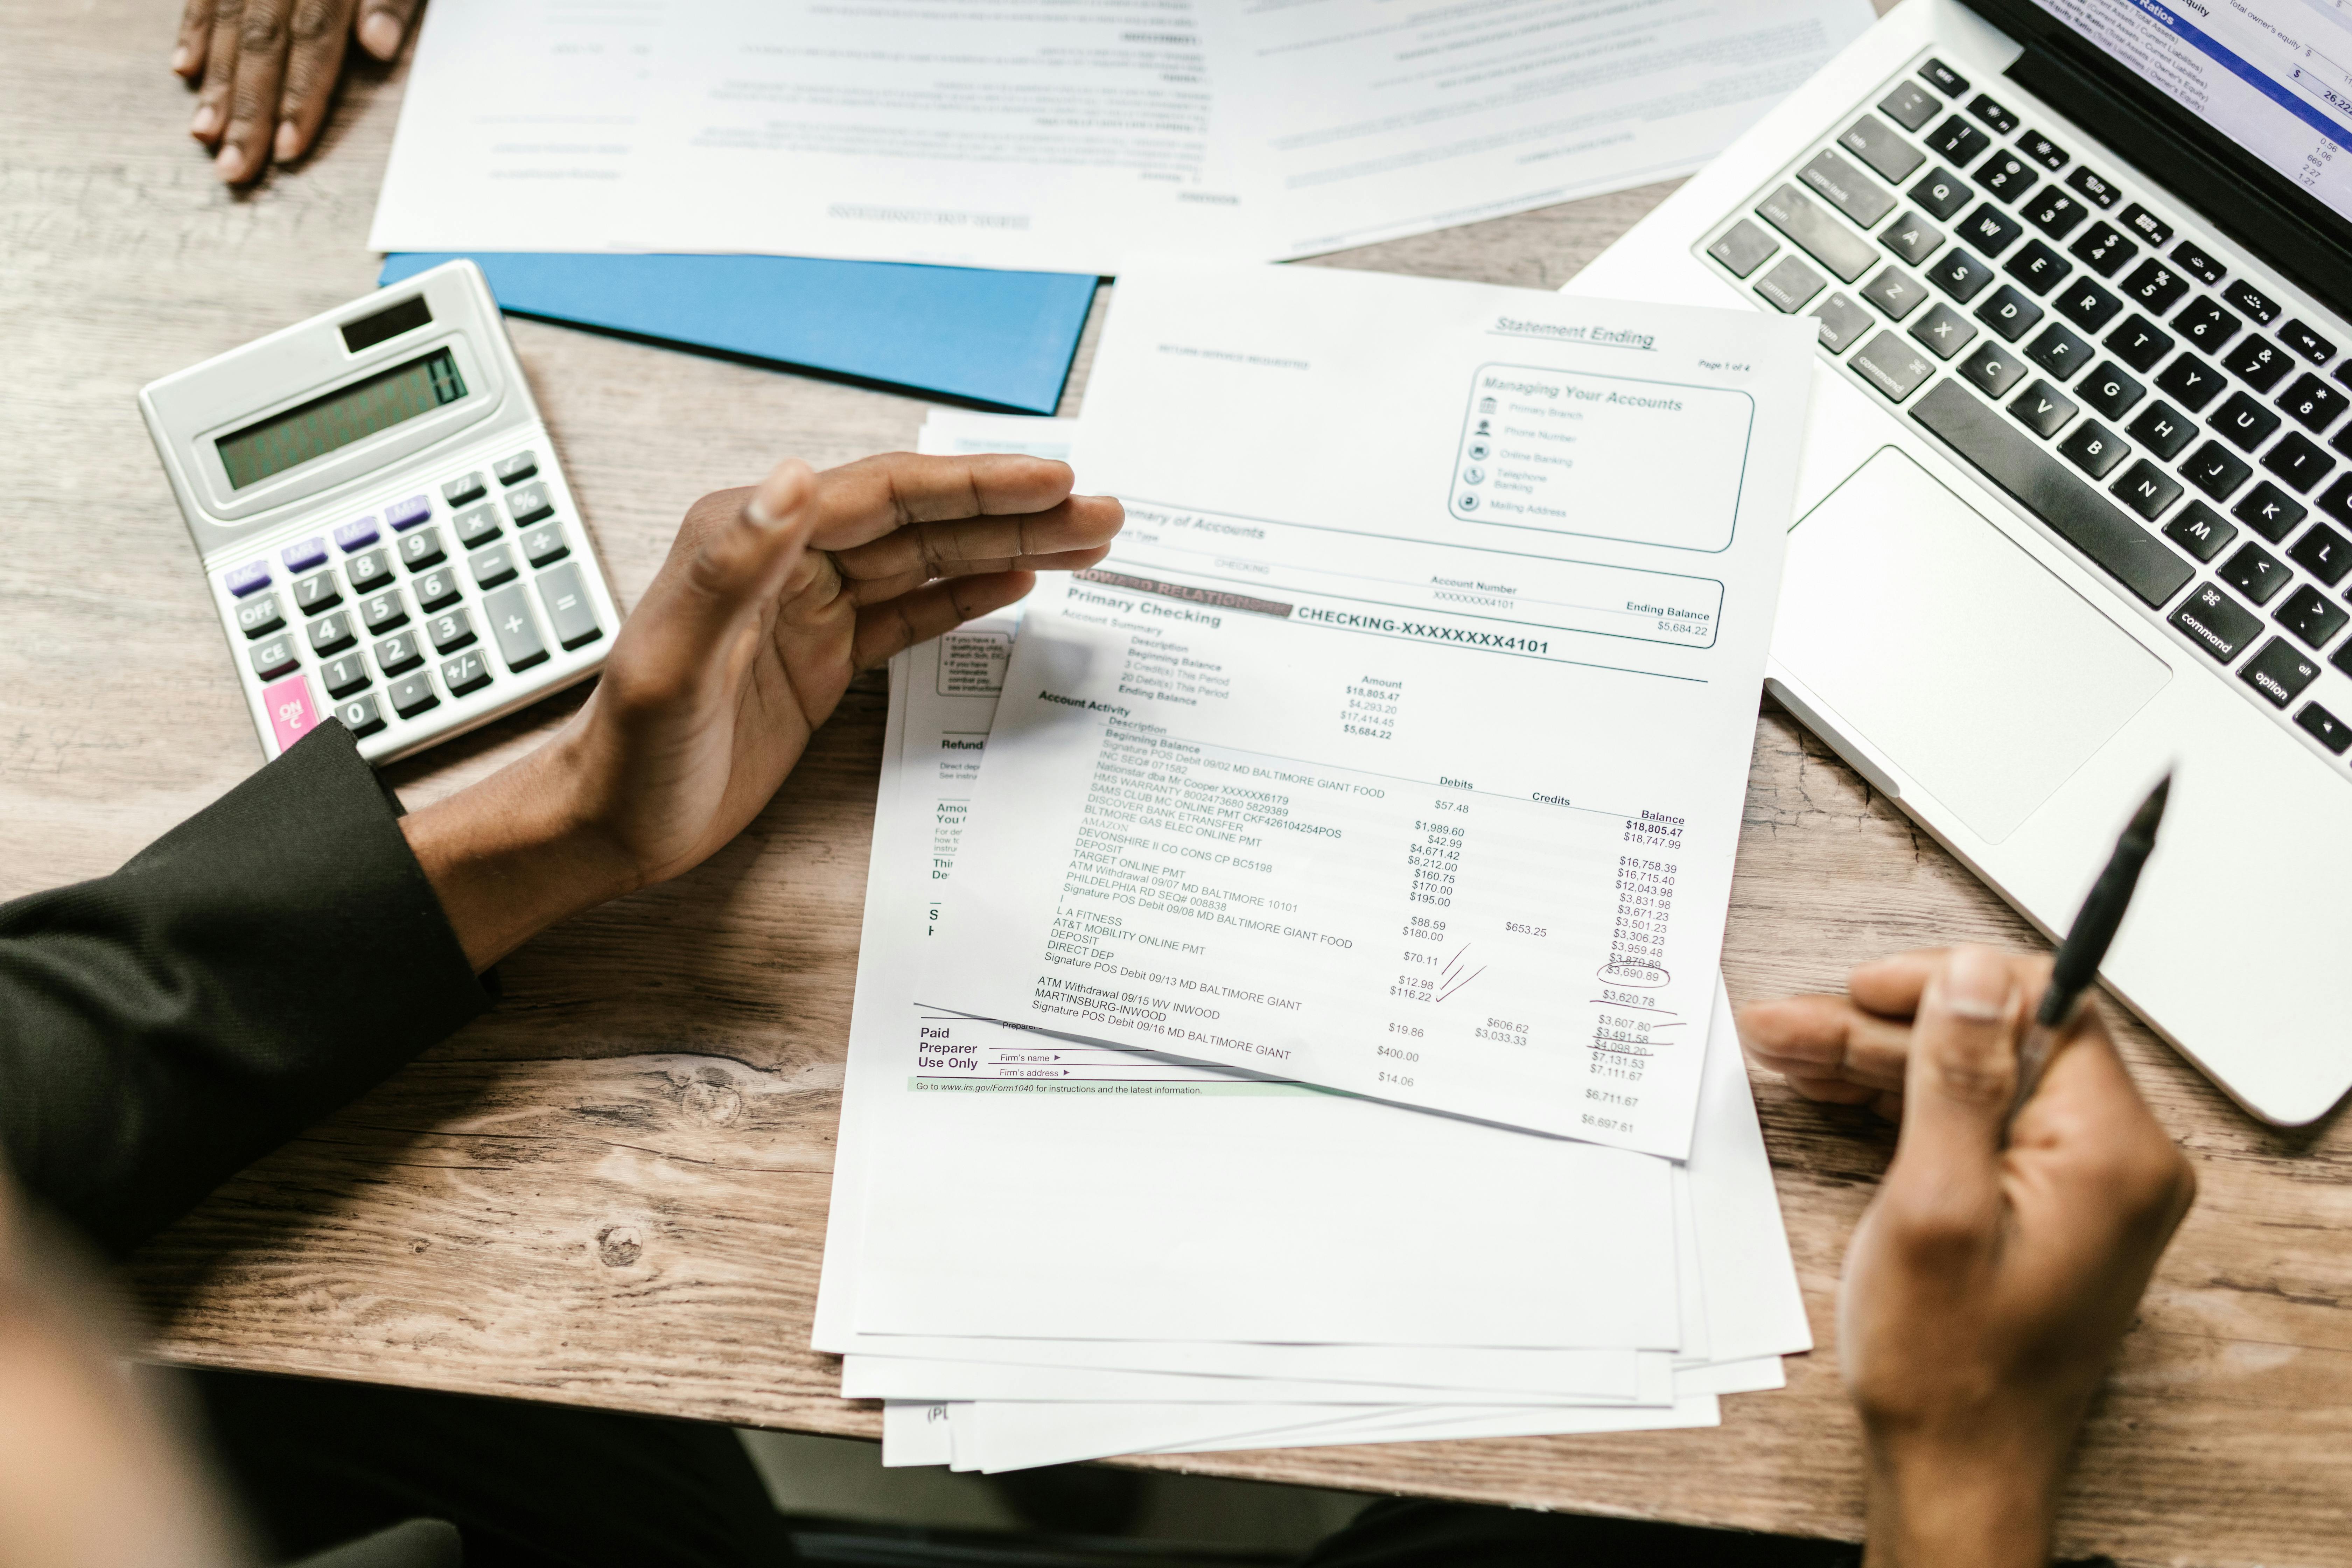
Reading a merchant statement shouldn’t require a finance degree. The rate a processor quoted you when you signed up is seldom what you actually pay, and the number that matters your effective rate, total fees divided by total card volume almost never appears anywhere on the statement itself. That’s not an accident. Your merchant statement is built to make the real number hard to find, and the pricing model behind it (tiered, flat-rate, or interchange-plus) determines exactly how the cost gets hidden.
This page walks through how to actually read a merchant statement, calculate your real effective rate, see what’s normal for your type of business, and spot the specific fees worth questioning.
The biggest reason businesses overpay for payment processing is surprisingly simple: they rarely stop to check what they’re actually being charged. Rates creep upward through small, individually unremarkable adjustments: a fraction of a point here, a new line-item fee there, and no single change is big enough to trigger a review on its own. A processor doesn’t need one obvious price hike. It just needs several small ones that never get added up.
The single highest-leverage thing a business can do about processing costs isn’t negotiating a better rate. It’s the ten minutes of math almost nobody does.
Here’s the part most guides on this topic skip entirely: it’s not just that statements are confusing; some of them contain numbers that are simply wrong, on purpose. A merchant statement isn’t standardized and isn’t regulated by any single agency, so no one is checking it for accuracy but you.
Two real, documented problems show up repeatedly:
One real documented statement audit found $270/month in padded interchange, $80/month in inflated assessment fees, and $870/month in additional charges that appeared nowhere in the original signed agreement — $1,220 a month, over $14,000 a year, that the business had no way of catching just by glancing at the total.
This is exactly why the effective-rate calculation below matters more than trying to verify each individual line on your merchant statement. You may not be able to confirm whether the “interchange” number on it is real. You can always confirm the bottom-line reality: total fees divided by total volume, regardless of how the processor chose to itemize it.
The formula is simple. Finding the right numbers on your merchant statement is the part that actually takes effort:
(Total Fees ÷ Total Card Volume) × 100 = Effective Rate
For example: $1,800 in total fees on $60,000 in card volume for the month = 3.0%.
The catch is that “total fees” means every fee line on your merchant statement, not just the one labeled “processing fee.” Statement terminology isn’t standardized across processors; the same charge might show up as “discount fee,” get split across multiple lines, or hide inside a monthly summary that doesn’t itemize. Add up every dollar that left the account because of card processing, not just the line that’s easiest to find.
One more practical note: pull 2–3 consecutive months before drawing a conclusion. A one-off annual PCI fee or a slow month can distort a single month’s number enough to be misleading either direction.
| Business type | Typical effective rate range |
|---|---|
Retail (general) | 1.5% – 2.4% |
Restaurant | ~2.0% average, up to 3.1% with a rewards-card-heavy customer base |
E-commerce | 2.3% – 3.5% (higher due to card-not-present fraud risk) |
B2B / high-ticket (without enhanced data) | ~2.9% |
B2B / high-ticket (with full line-item data) | ~1.9% |
These are typical ranges, not guarantees; your actual number depends on your real card mix, ticket size, and how the account is set up. But if your calculated effective rate is sitting well above the range for your business type, that’s a real, specific signal worth investigating, not just a vague feeling that fees seem high.
Some fees are legitimate. Some are pure markup dressed up to look legitimate. Here’s how to tell the difference:
None of these individually looks alarming on a statement. Add several together, though, and it’s realistic for a business to be paying well over $100/month in fees that arrived before a single transaction was even counted $1,200 or more a year, on top of the actual processing rate.
If your business runs B2B or high-ticket commercial-card volume, there’s a real, recent shift worth knowing: Visa retired its standalone Level 2 interchange discount program in April 2026, folding it into the Commercial Enhanced Data Program (CEDP) a change that started rolling out with new data-validation requirements in late 2025.
The practical effect is that submitting only basic Level 2-style transaction data no longer earns a discount on Visa commercial cards. Full line-item detail is now the only path to the lower rate. A business that hasn’t updated how it submits transaction data since before this change may be paying the higher, non-discounted rate without realizing anything changed.
A $30,000/month restaurant sitting at a 3.2% effective rate is paying about $960/month, or $11,520/year, in processing fees. The same restaurant at a well-negotiated 2.2% rate (interchange-plus, no junk fees layered on) would pay about $660/month, or $7,920/year, a $3,600/year gap from the rate alone, before even counting what gets eliminated by clearing out junk fees.
On the B2B side, a business moving $100,000/month in commercial-card volume from basic Level 1 processing to full CEDP-qualified data can save roughly $1,000/month — $12,000/year purely from how the transaction data is submitted, with nothing else changing about the underlying rate.
There’s also a third option beyond just negotiating a better rate: see our guide to dual pricing to find out how some businesses eliminate the card processing fee entirely.
Want an actual merchant statement review instead of doing the math yourself? Get a free comparison →effective rate merchant statement
Millions of businesses get paid somewhere other than a store with reliable wifi, a customer’s driveway, a job site, a food truck window, a trade show floor. The good news: in the vast majority of those situations, you don’t actually need wifi at all. A phone or tablet on cellular data alone can process a real-time card payment just as securely as one sitting on a store’s internet connection.
This page covers how mobile payments actually work without wifi from a simple cellular connection, up through a true last-resort offline mode and the real risk that last option carries, which most sales pitches leave out.
It’s worth separating these clearly, because the right solution is different for each. Most “no wifi” situations still have a cellular signal; a phone or tablet can process a payment over 4G/LTE exactly the same way it would over wifi, with the same real-time authorization.
True dead zones, where there’s no signal of any kind, are a much smaller, specific problem, and they’re more common than most people assume: per the FCC’s own 2026 broadband data, combined 5G and broadband coverage reaches 98% of urban areas but only 61–71% of rural areas. For any business that regularly works job sites, routes, or rural service calls, that gap is a real, practical planning issue, not a rare edge case.
These aren’t equally reliable, and it matters which one you’re actually counting on:
For most businesses, the first two options cover nearly everything. Store-and-forward exists specifically for the real dead zones, and it comes with real limitations worth understanding before relying on it.
Store-and-forward has to be turned on deliberately; it’s not the default, because of the real fraud risk it introduces. Once enabled, a customer’s experience doesn’t change: they tap, dip, or swipe exactly as normal. Behind the scenes, the transaction data is stored securely on the device instead of being sent for authorization immediately. As soon as the device reconnects to a signal, the system automatically sends every stored transaction through for real authorization.
Here’s the part that matters most and gets glossed over the most: an offline transaction isn’t actually approved at the moment it happens; it just looks that way to the customer. The real authorization doesn’t happen until the device reconnects and the transaction is actually submitted, which means it’s possible for a card to come back declined after the sale already felt complete.
There’s also a real-time limit: stored offline transactions typically have to be submitted within 24 to 72 hours, depending on the processor and system. Anything that doesn’t reconnect within that window is dropped automatically and simply never gets collected. Because of that real risk, offline mode works best with deliberately low transaction limits, and is best suited to smaller-ticket sales where the occasional lost transaction is a manageable, bounded risk, not one that could sink a large sale. Treat it as a genuine backup for real dead zones, not a primary way of doing business.
Mobile payments away from wifi isn’t a general retail concern; it’s specifically relevant to businesses that collect payment in person, on-site, where the sale itself happens away from a fixed location with reliable internet: field service technicians and contractors, home services, food trucks, and businesses working trade shows, fairs, or rural routes. (This is different from delivery orders placed online or by phone; those are already paid for at the time of ordering, so the driver isn’t the one collecting payment.)
The field service industry alone supports an estimated 19 million-plus technicians in the U.S. A real, large population of workers who need a way to get paid wherever the job actually is, not just back at an office. Because Tap to Pay works directly on a regular iPhone or Android device, with no separate card reader or terminal to buy, carry, or charge, the phone already in someone’s pocket can be the entire mobile payments setup, with cellular data (or, as a real backup, store-and-forward) included.
Since you’re processing cards wherever the job is, it’s also worth knowing whether dual pricing could eliminate that cost entirely, no matter where you’re taking the payment.
Want to know what accepting payment away from wifi would actually look like for your business? Get a free comparison →

If your business regularly gets paid by a corporate, purchasing, or commercial card not a regular consumer card — there’s a real, published discount available on those transactions called Level 3 processing. Most businesses that qualify never actually claim it, because it requires sending more information with each transaction than a standard card swipe collects.
This page covers what Level 3 actually is, what it takes to qualify, and real, published Level 3 rates showing exactly what the discount is worth.
Before Level 2 or Level 3 even enters the picture, a business, purchasing, or corporate card already carries a meaningfully higher base cost than a regular consumer card because it’s underwriting a different kind of risk and, often, purchase controls the issuing bank has to manage. To put a real number on that gap: Visa’s own published interchange schedule puts a large-bank-issued (regulated) consumer debit card at 0.05% + $0.21 per transaction, versus a corporate or purchasing card with no enhanced data attached at 2.70% + $0.10. That’s the real starting point for a B2B or B2G supplier a meaningfully higher baseline cost than a typical retail transaction, before any discount is even in play.
A basic card transaction (sometimes called Level 1) sends the network almost nothing beyond the card number, the total amount, and the date. Level 2 and Level 3 are simply more information sent along with the same transaction, and the card networks reward that extra detail with a lower rate, because it’s the same information a purchasing department already wants for its own records:
Under Visa’s current commercial card program, real published Level 3 rates show exactly what qualifying is worth. The higher number is what you pay with basic Level 1 data; the lower number is the same transaction with full Level 3 data attached:
| Transaction type | Level 1 (no enhanced data) | Level 3 (qualified) |
|---|---|---|
Purchasing, non-travel | 1.90% + $0.10 | 1.75% + $0.10 |
Purchasing, large ticket | 1.45% + $35 | 1.30% + $35 |
NMI, the payment gateway behind a large share of B2B card processing, puts the combined real-world savings from Level 2 and Level 3 data together at roughly 50 to 150 basis points (hundredths of a percent) versus a non-qualified commercial transaction, scaling with transaction size. On a business running meaningful purchasing-card volume, that’s not a rounding error; it’s a real, recurring reduction in what every qualifying transaction actually costs.
This is the part that trips up a lot of businesses: the two networks have genuinely diverged. Visa has been consolidating its enhanced-data programs into something called the Commercial Enhanced Data Program (CEDP), rolled out in 2025 and tightened further since, including a requirement that qualifying data actually be accurate and complete, not generic placeholder values. Visa’s standalone Level 2 program is being phased out entirely, meaning full Level 3 data is increasingly the only path to a discount on a Visa commercial card.
Mastercard, by contrast, still recognizes Level 2 and Level 3 as separate tiers, each with its own rate reduction. Practically, that means a business that accepts both Visa and Mastercard purchasing cards can’t assume one setup automatically covers both; it’s worth confirming your payment system is actually submitting the right level of data to each network separately, not just checking a single “enhanced data” box.
The most common reason a business misses this discount isn’t ignorance that it exists; it’s a payment system that isn’t actually built to capture and send Level 3 data in the first place. A basic card terminal or a simple online checkout typically doesn’t have anywhere to enter line-item detail, tax amount, or a PO number, so every transaction defaults to the lowest, least-qualified rate automatically. And under Visa’s current rules specifically, submitting blank or placeholder data doesn’t help; a transaction has to include real, accurate detail to actually qualify, not just technically include the right fields.
This isn’t relevant to every business; it’s specifically valuable for B2B suppliers, wholesalers, and government contractors (B2G) who regularly get paid by corporate, purchasing, or commercial cards rather than ordinary consumer cards. If that’s a meaningful share of how your business gets paid, the invoicing and payment setup discussed in our guide to speeding up accounts receivable is the same place this data can flow from. A system built to capture full line-item invoice detail for faster collection is often the same system that can automatically submit that same detail for Level 3 qualification, at no extra effort once it’s set up correctly.
Want to know whether your business is missing out on Level 3 rates right now? Get a free comparison →
In 2025, 44% of B2B invoices in the U.S. are overdue, and 3% never get collected at all and are written off as bad debt. That’s not mostly a collections-department problem. For a lot of businesses, it’s an accounts receivable friction problem: the invoice asks the customer to write a check, find a stamp, and mail it, in a world where almost everything else gets paid with one tap. This page covers how slow B2B collection really is, what actually speeds it up, and the specific tools: QR codes, emailed and texted payment links, and a genuinely different way to handle ACH that turn a 45-day wait into something much shorter.
Late B2B payments don’t stay contained to the customer who’s late. According to the Atradius Payment Practices Barometer US 2025, when late payments pile up, 42% of U.S. companies say they then struggle to meet their own financial obligations, and 40% end up slowing payments to their own suppliers. It becomes a chain reaction: one business’s slow accounts receivable turns into another business’s slow accounts payable. That’s the real reason collection speed matters beyond just “getting paid faster.” It’s about not becoming the next link in that chain.
The numbers are worse than most owners assume until they actually look:
| What the real data shows | Figure |
|---|---|
B2B invoices currently overdue in the U.S. (2025) | 44% |
U.S. businesses saying time-to-get-paid has gotten worse | 34% |
Credit-based B2B sales overdue for U.S. companies | 43% |
(Source: Atradius Payment Practices Barometer US 2025 and Atradius B2B Payment Practices Trends, USMCA 2025.)
There’s also a real, measurable gap between typical and best-in-class collection speed. The Hackett Group’s 2025 Working Capital Survey found the average cash conversion cycle (the plain-English version: how many days of cash a business has tied up between paying its own costs and actually collecting on its sales) sits at 89 days across more than 2,700 public U.S. companies, but the 1,000 largest, most collection-efficient companies average just 37 days. That’s not a difference in customer quality. It’s largely a difference in how easy those companies make it to actually pay them.
This isn’t guesswork; it’s been measured directly. PYMNTS and American Express surveyed 460 businesses for their B2B Payments Innovation Readiness study and found that among businesses that had automated their accounts receivable process, about two-thirds reported a real improvement in DSO (days sales outstanding the average number of days it takes to collect payment after a sale), and about half reported lower delinquency rates.
The common thread across every business that saw real improvement wasn’t a new collections script or a more aggressive follow-up policy. It was removing friction from the actual moment of paying.
A mailed paper invoice asks a customer to do several things before you see the money: open the mail, write a check, find an envelope and a stamp, and remember to actually send it each one a place the payment can stall for days or get forgotten entirely. A digital payment option collapses that whole sequence into one tap, from wherever the customer already is: their email, their phone, or literally the invoice itself.
These aren’t hypothetical features; they’re real, available tools that plug directly into how you already invoice:
For a large B2B invoice specifically, how the payment is priced matters as much as how it’s sent. A card payment is typically priced as a percentage of the sale, fine for a small transaction, expensive on a large one. ACH (a direct bank-to-bank transfer) can instead be priced as a flat fee per transaction, regardless of the invoice size; a five-hundred-dollar invoice and a fifty-thousand-dollar invoice cost exactly the same to collect. On a large invoice, that’s a meaningfully cheaper way to collect than a percentage-based card fee. (This comparison applies to a standard processing setup; if you’re already using dual pricing, the card fee is passed to the card price rather than coming out of your own margin, so the calculation is different.)
If a meaningful share of what you collect comes in on commercial or purchasing cards specifically, see our guide to Level 3 rates for a real discount most businesses never claim.
Want to see what faster B2B collection would actually look like for your invoicing? Get a free comparison →
When 72 real restaurant owners and operators were asked what actually matters in their restaurant POS system, the top answer wasn’t a feature list or a brand name; it was simply being easy to use. Half of respondents named “easy to use” or “simplicity” as what they valued most, well ahead of reporting tools, cloud access, or anything else on the feature sheet. And here’s the part that surprises people: nearly half of restaurant owners say they wouldn’t even consider switching systems, not necessarily because their current POS is great, but because switching is its own real hassle most owners would rather avoid.
This page covers what real restaurant owners say actually matters, why so many stay on a system they’re not thrilled with anyway, and, just as important, what actually pushes the ones who do switch to finally make the change, all from real operator survey data, not a vendor feature comparison.
Over half the restaurant owners surveyed had been on their current POS for five years or more, ten of them for over two decades. That’s not necessarily loyalty to a great product. It’s often just the honest math of switching: retraining every employee, re-entering a menu, and living through an awkward transition period, all while still running a restaurant every single day.
37% named employee training as the single biggest barrier to switching, and another 18% pointed to the transition process itself. Staying put isn’t always a vote of confidence; a lot of the time, it’s just avoiding a headache that hasn’t become unbearable yet.
| What restaurant owners say matters most | % citing it |
|---|---|
| Easy to use / simplicity | 50% |
Reporting tools and cloud/mobile access, combined | 18% |
No real complaints with current system | 25% |
Notice what’s not at the top: an advanced feature list. Owners running a real restaurant, day in and day out, consistently value a system that a new hire can actually learn fast over one that does the most things on paper.
The survey also asked owners to rate their own systems directly, and the numbers tell a more specific story than “most people are satisfied”:
| Satisfaction Area | Real Result |
|---|---|
| Ease of use/reliability rated 7+ out of 10 | 72% |
Technical support rated 8+ out of 10 | 61% |
Support rated below 5, or no real support access at all | 14% |
When owners did complain, the pattern was consistent: systems that were glitchy, unreliable, or lost connectivity, especially during a dinner rush, exactly when a slow or frozen screen costs the most. Poor support was the other repeat theme: long hold times, tickets that drag on, and reps who don’t seem to understand a restaurant’s actual day-to-day problems. Neither of those is a fancy-feature complaint. They’re both “does this basic thing reliably work when I need it to” complaints, which tracks with simplicity and reliability topping the priorities list above.
Inertia doesn’t win forever. Hospitality Technology’s 2026 POS Software Trends Study found nearly 44% of restaurant operators plan to replace or significantly upgrade their restaurant POS. Among operators who’d already gone through with a switch, the reasons were concrete, not vague dissatisfaction: 60% pointed to features and functionality their old system simply couldn’t do, and 57% pointed to better pricing or lower fees available elsewhere. In plain terms: restaurants switch when the old system is genuinely holding the business back, or when it’s genuinely costing more than it needs to, not on a whim.
The same research also shows what makes operators hesitate even once they’re ready to make a change: system reliability (30%), high upfront cost (29%), and integration with other systems (26%) were the top real concerns about the new system, not the old one. That’s useful to know before you start shopping; it means the right questions to ask a new provider aren’t about features at all. They’re “will this actually stay up during a Friday rush,” “what does this really cost all-in, not just the advertised rate,” and “does this talk to the other tools I already use.” A provider who can answer those three clearly, in writing, before you sign is solving the actual thing that makes owners hesitate, not just pitching another feature list.
Most of what gets written about restaurant POS systems is really written with a multi-location or corporate operation in mind: dashboards for comparing stores, enterprise reporting, franchise-level rollout logistics. For a single, independently owned restaurant or diner, most of that is simply irrelevant. What matters instead is much closer to what the survey actually found: a system your staff can learn in a shift or two, that doesn’t go down during a Friday night rush, and where a real person picks up the phone when something breaks, not a ticket queue.
That’s also where an independent restaurant has a genuine advantage a chain doesn’t: the freedom to actually pick the system and the support relationship that fits how your specific restaurant runs, instead of whatever corporate standardized on for a hundred locations.
One more thing worth knowing before you sign anything: many all-in-one restaurant POS providers not just one company; this is common industry-wide require payment processing to run through them as part of the package, rather than letting you keep a separate processor. That’s a fair trade-off to understand upfront, not something to discover halfway through a decision.
If you’re evaluating a new restaurant POS, it’s also the natural moment to look at what you’re actually paying to process cards (see our guide to reading a merchant statement) and whether dual pricing makes sense for your restaurant. If you’re replacing an existing system rather than buying your first one, our guide to switching POS systems without downtime covers what that transition actually looks like, including the training-time planning that real owners say matters most.
Want to know what a restaurant POS switch would actually mean for your processing costs and setup? Get a free comparison →